INSURANCE CLAIMS IN HOUSTON
GET YOUR FREE ESTIMATE
Fill out the below form and we’ll respond back to you shortly.
How does a hail claim work in Texas?
Hail is a covered peril on nearly every Texas homeowners policy, and most policies now require the damage to be reported within one year of the storm date. You file with your carrier, an adjuster inspects the roof, and the carrier pays the approved scope minus your deductible, often holding back recoverable depreciation until the work is finished. Under Texas Insurance Code §707.003 no contractor may waive or pay your deductible, so on an approved claim your cost is the deductible and nothing more.
The Roof Claim Process, Step by Step
- 1. Free roof inspectionWe walk every slope and check the attic before you call anyone. If there is no storm damage, we tell you so and you have not opened a claim on your record for nothing.
- 2. Photo documentationEvery hit, creased tab, dented vent and lifted ridge cap is photographed and labeled by slope, alongside the storm date it lines up with. That report is yours to keep whether or not you hire us.
- 3. File with your carrierYou call the claims line or file online, give the date of loss and a short description. The carrier issues a claim number and assigns an adjuster.
- 4. Adjuster meetingWe meet the adjuster on the roof at no charge and walk the damage slope by slope, so the inspection covers what is actually there and not only what shows from the ladder.
- 5. Approval and scopeThe carrier sends its estimate, line by line. We compare it to the roof and to the photo report, and if items are missing (drip edge, starter, ridge vent, code-required underlayment) we send a supplement with photos before work is scheduled.
- 6. The buildWith the scope agreed and HOA approval in hand, most homes are torn off and re-roofed in a single day, with new underlayment, flashing and ventilation as approved.
- 7. Final invoice and depreciationWe send the final invoice and completion photos to your carrier, which releases the recoverable depreciation it held back. We also help with mortgage-company endorsements on the checks.
What a Texas Roof Claim Covers
Usually covered
- Hail bruising and fractured shingle mats (functional damage)
- Wind-creased or missing shingles, broken seal strips and torn-off ridge caps
- Storm-damaged vents, pipe jacks, flashing and gutters
- Tear-off, underlayment, drip edge and disposal as part of the replacement
- Reasonable emergency tarping to stop further damage
- Interior water damage caused by the storm opening
- Code-required items, if your policy carries ordinance or law coverage
Usually not covered
- Age, wear and tear, and granule loss from normal weathering
- Leaks from old or poor workmanship that pre-date the storm
- Cosmetic dents on metal, where the policy has a cosmetic-damage exclusion
- Damage reported after the policy's deadline
- Upgrades you choose beyond like-kind replacement (you can pay the difference)
Roofs past 10 to 15 years are often on actual-cash-value coverage, which pays replacement cost minus depreciation and does not release it later. Your declarations page says which you have.
How Long a Roof Claim Takes
Texas sets deadlines for the carrier under Chapter 542 of the Insurance Code. They run from when the carrier receives your claim and the documents it asks for, and they stretch by 15 days after a weather-related catastrophe declared by the insurance commissioner.
| Stage | Typical timing in Texas |
|---|---|
| Report the damage | Within your policy's window: one year from the storm date on most Texas policies |
| Carrier acknowledges the claim | Within 15 days of notice, and starts its investigation |
| Carrier accepts or denies | Within 15 business days of receiving everything it requested (up to 45 more days if it explains why) |
| First payment | Within 5 business days of accepting the claim |
| Roof installation | Most homes are torn off and re-roofed in one day once the scope and HOA approval are in |
| Depreciation released | After the final invoice and completion photos reach the carrier; check your policy for its deadline |
Do I Need to Pay My Deductible?
Yes. Texas Insurance Code §707.003 prohibits a contractor from paying, waiving, rebating or absorbing any part of your deductible, whether it is offered as a discount, a rebate or a padded invoice. A roofer who offers to cover it is breaking the law, and the carrier can deny the claim over it.
Texas wind and hail deductibles are often a percentage of the dwelling coverage, commonly 1% to 2%, so check your declarations page before you file. If the deductible is the hurdle, it can be financed like any other part of the project.
Related Storm and Inspection Guides
- Hail and storm damage roof repair in Houston: The storms still producing claims, what hail and wind do to shingles, and what to do first.
- Free roof inspection in Cypress and Houston: What we check, how long it takes, the photo report you keep, and when to book one.
ABOUT INSURANCE CLAIMS
We have over 11 years experience working with insurance companies on hail and wind claims in Houston and the surrounding areas. In many cases, we have assisted insurance companies with identification of damage and estimating the claim. We know what to look for, how to process your claim and make sure you get the funds necessary to compensate for your losses.
Houston Strong Roofing L.L.C. has handled thousands of insurance claims. You are in good hands with our knowledgeable staff. We will be glad to help you with your claim and explain anything you may have questions about. If you already have a claim, you can contact us for a free, no obligation claims assessment. We do not charge for meeting with your insurance adjuster to fight for your claim. We only ask that we do the work once we receive the insurance company’s approval.
SERVICE FEATURES
Our highly experienced and skilled team is here to help you with your insurance claim at any stage of the process. Before you begin repairs it is imperative that your insurance settlement is accurate and the scope of work includes everything necessary to fully restore your property.
Meet with the Insurance Company’s adjuster to assess damage and discuss proper restoration, review claim estimate for accuracy and appropriateness of repairs recommended
Employ or recommend Public Adjusters, Attorneys, Engineers, trades experts when needed and consult throughout the process to ensure you are fully informed and fairly treated
Collect additional depreciation funds held by insurance, assist with mortgage company endorsements and inspections, and bring the entire project to completion
Financing Available!
Make your roofing project more affordable with our flexible financing options. We work with trusted lenders to offer competitive rates and convenient payment plans that fit your budget.
Roof Insurance Claims by Houston Neighborhood
A roof claim in Houston is not one process. What the adjuster looks for, what gets missed, and what the settlement has to cover depend on when the neighborhood was built, what is growing over it, and which county issues the permit. These are the areas where we work claims most often, and what we run into in each.
The Woodlands and Spring
Montgomery County claims under the pine canopy are dominated by limb strikes and debris, not hail. Adjusters here look for punctures and crushed ridge lines before they look for bruising.
- Grogan's Mill and Panther Creek. The oldest villages, with mature pines over 1970s and 80s roofs. Limb damage is usually concentrated on one slope and is often under-scoped on the first adjuster visit.
- Alden Bridge and Sterling Ridge. 1990s and 2000s builds where wind-lifted shingles and broken seal strips are the typical finding after a named wind event.
- Champion Forest and Klein. Spring's larger 1970s and 80s homes; the claim question is usually whether the decking under the damage has to be replaced, which changes the settlement significantly.
Cypress and Northwest Houston
Harris County, and the part of the metro that took the May 2024 hail hardest. Most claims we work here are hail bruising on 1990s and 2000s architectural shingle roofs.
- Tower Oaks Meadows, Harvest Bend and Windfern. 1980s and 90s subdivisions off 249 and 1960. Roofs of that age with hail bruising are usually a full replacement claim rather than a repair.
- Lakes on Eldridge and The Parkway at Eldridge. Gated communities with HOA architectural review; we handle the color and material approval as part of the claim.
- Jersey Village and Meisterwood. Mid-century Jersey Village roofs and the newer neighborhoods around it. Older low-slope sections need their own line items in the scope or they get left out.
- Silver Oak Trails and Bridgeland. Newer construction; claims here are more often wind than hail, and builder-grade installation issues sometimes surface during the adjuster meeting.
Katy and West Houston
Split between Harris and Fort Bend County, which matters for permits after the claim is approved. West Houston took the May 16, 2024 derecho at full strength.
- Kelliwood, Kelliwood Oaks and Katyland. Established Katy neighborhoods with large trees; wind and limb damage claims, frequently with damaged gutters and fascia that belong in the scope.
- Westheimer Lakes North and South. 2000s Fort Bend County builds on open ground with real wind exposure. Straight-line wind claims after the derecho were common here.
- Mission Bend and Alief. 1970s and 80s homes, many on their second or third roof. Depreciation and roof age come up in nearly every claim, and we document the pre-storm condition carefully.
Inside the Loop and the Memorial corridor
Older housing stock and higher-value homes. Claims here are less about volume and more about getting the scope right on complex roofs.
- Braes Heights and Southside Place. 1950s ranch homes, many with low-slope additions. Low-slope sections have their own materials and are the most commonly under-scoped part of a claim here.
- Timbergrove and Spring Branch. Mid-century homes under heavy tree cover; limb damage and clogged-valley leaks that predate the storm need to be separated from the storm claim honestly.
- Bayou Woods and the Memorial villages. Larger, steeper roofs, often tile or high-end shingle. Matching materials on a partial replacement is a claim negotiation in itself.
Not listed? We work claims across the whole metro. The process is the same everywhere: a free inspection with a photo report, then we meet your adjuster on the roof. Start with the free inspection request, or read about recent Houston storms to check whether your roof was in the path.
RECENTLY COMPLETED PROJECTS
Roof Replacement on Wildbrook Canyon Ln in Katy, TXSeptember 2026
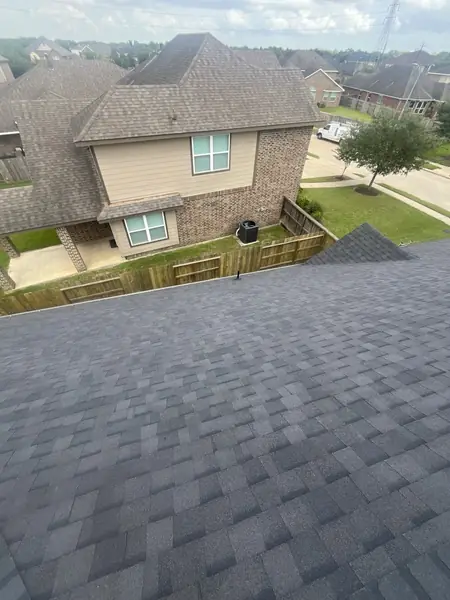
Roof Replacement on Hughes Ranch Rd in Houston, TXSeptember 2026
Roof Replacement on Glascow Grn in Houston, TXSeptember 2026
Roof Replacement on Clareton Ln in Cypress, TXSeptember 2026
Roof Replacement on Sageaspen Ln in Houston, TXAugust 2026
Roof Replacement on Sage Dale Dr in Houston, TXAugust 2026
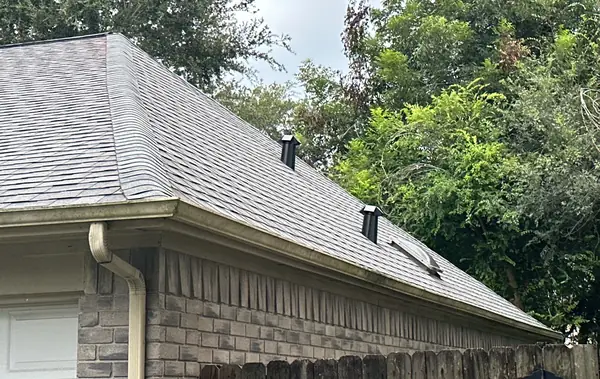
Roof Replacement on Rainbow Run in Sugar Land, TXAugust 2026
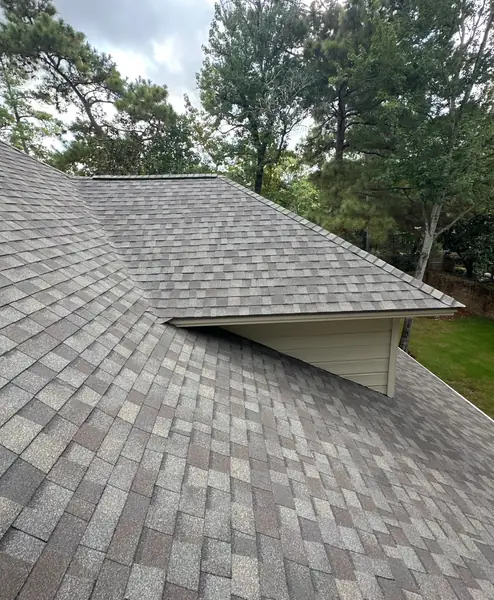
Roof Replacement on Pleasant Creek Dr in Houston, TXAugust 2026
FAQS
Common questions about roof insurance claims in Texas.
Will my insurance company pay for my roof to be replaced?
Most policies cover roof replacement when damage comes from a covered peril such as hail, wind, or storm. We document the damage thoroughly and work directly with your carrier so the full scope gets accounted for.
Does it matter how old my roof is?
Roof age can affect how a claim is settled — older roofs may have depreciation applied — but significant storm damage is typically covered regardless of age. We'll help you understand your specific policy situation.
How much do I have to pay?
Typically your insurance deductible. After that, your carrier covers the remaining approved costs. Texas law prohibits contractors from paying, waiving, or rebating any part of your deductible, and we follow that strictly.
Do you meet with the insurance adjuster?
Yes. We walk the roof with your adjuster so the full extent of the damage is documented — not just what's visible from the ground. This is where most under-scoped claims get corrected.
What if my claim gets denied?
A denial isn't always final. We'll review the adjuster's report with you, and if damage was missed or misclassified, we can provide documentation to support a re-inspection. Financing is also available if you decide to move forward independently.
How do I file a roof insurance claim in Texas?
Get the roof inspected and documented first, then call your carrier's claims line and give them the storm date and a description of the damage. They assign an adjuster and schedule an inspection. We attend that inspection, walk the roof with the adjuster, and make sure the scope reflects what is actually there. After the estimate arrives we review it with you before any work is scheduled.
What is the difference between a hail claim and a wind claim?
Both are covered perils on most Texas policies, but they leave different evidence. Hail bruises the shingle mat and dents the metal; wind creases tabs, breaks seal strips and strips ridge caps. Some policies carry a separate, higher wind and hail deductible, often a percentage of the home's value, so it is worth checking which applies before you file.
How long does a roof insurance claim take in Texas?
Under Chapter 542 of the Texas Insurance Code, the carrier has 15 days to acknowledge your claim, 15 business days to accept or deny it once it has the documents it asked for (up to 45 more days if it explains why), and 5 business days to pay after accepting. Once the scope is approved, the roof itself usually goes on in one day.
Can a roofer pay or waive my deductible in Texas?
No. Texas Insurance Code §707.003 prohibits a contractor from paying, waiving or rebating any part of your deductible, in cash, as a discount, or through a padded invoice. Your out-of-pocket cost on an approved claim is the deductible, and it can be financed.
Do you handle claims outside Cypress?
Yes. We work claims across the Houston metro, from The Woodlands and Spring to Katy, Jersey Village, Braes Heights and the Memorial villages. The process is the same everywhere: free inspection, photo report, adjuster meeting on the roof.
Storm Damage Repair by Area
What we run into varies a lot by market. These pages cover the specifics for each one.
- Storm Damage Repair in CypressStorm Claims in Cypress
- Storm Damage Repair in KatyKaty Storm Claims
- Storm Damage Repair in SpringLimb Damage and Insurance
- Storm Damage Repair in The WoodlandsDocumenting Limb Damage for a Claim
- Storm Damage Repair in HoustonInsurance Claims Across the Metro
- Storm Damage Repair in ConroeWhat the 2024 Storms Did in Conroe
Other Roofing Services We Provide
- Roof ReplacementFull tear-off and replacement, most homes finished in a day.
- Roof RepairsLeak diagnosis and fast, honest repairs with upfront pricing.
- Roof InspectionsFree photo-documented inspection of your roof's real condition.
- Roof MaintenancePreventive care that gets full life out of your roof.
Serving Cypress, TX, The Woodlands, TX, Spring, TX, Katy, TX, Conroe, TX, Houston, TX.
WHY CHOOSE US
In Cypress
Since 2013
Decades of combined roofing and restoration experience, serving Houston-area homeowners from Cypress since 2013.
Uncompromising
Quality
We use top-tier materials and advanced roofing techniques with focus on durability and longevity of every roof system.
Insurance
Specialists
Work directly with insurance adjusters and advocate for your best interests during insurance claim negotiations.
PROTECT YOUR HOME WITH HOUSTON STRONG ROOFING!
Fill out the form or call us today to get a free quote.
CALL US: (832) 271-7783GET YOUR FREE ESTIMATE
Fill out the below form and we’ll respond back to you shortly.