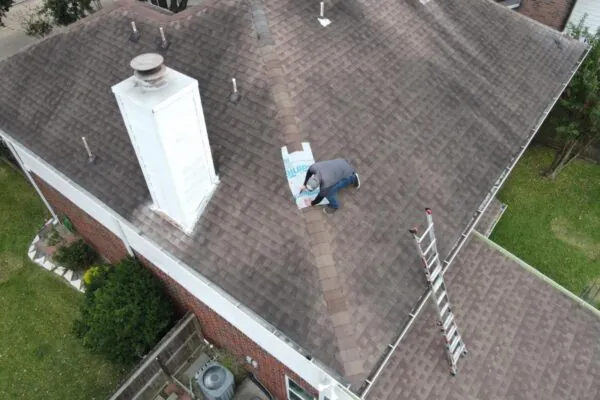
Roof Replacement Cost in Houston (2026): What Affects Your Price
Squares, pitch, material, tear-off layers, decking and permits: what each line of a Houston roof quote pays for, and when insurance covers the replacement.
Hail rarely leaves a hole. It leaves a roof that looks fine from the driveway and leaks two summers later. Here is how to tell, what it costs to fix, and how the claim works.
Free inspection, photos of what we find, and a written quote.
Every spring, hail crosses some part of the Houston metro, and every spring the same thing happens: a few homeowners get tarps on the roof within the week, and far more decide the roof looks fine and move on. A year or two later the ceiling stains show up, the policy's reporting window has closed, and a covered loss has become a $15,000 bill. This guide is written to keep you in the first group.
We are a Cypress-based roofing company that has worked hail and wind claims across northwest Houston since 2013. What follows is what we look for on the roof, what the 2024 storms did to roofs in our area, how the repair-or-replace decision gets made, what it costs, and what a Texas homeowners policy actually pays.
Hail does not usually punch through a shingle. It bruises it. A hailstone hitting at 60 to 90 miles per hour knocks the protective granules off a round spot and fractures the fiberglass mat underneath. The shingle still sheds water for a while. Then Houston sun works on the exposed mat, the bruise opens into a crack, and the leak appears one or two summers after the storm.
That delay is why hail damage is the most under-claimed roof loss in Texas. The roof looks intact from the ground, there is no leak, and nobody calls. By the time there is a leak, many policies have closed the window for reporting the storm.
Hail also strips granules in a wider pattern across a slope, which shortens the roof's life even where no single bruise is visible. On an older roof that is often the finding: no dramatic hits, but a roof that lost five years of life in one afternoon.
You should not go on the roof after a storm. Wet shingles and hidden decking damage put homeowners in the hospital every season. These checks can be done from the yard and tell most of the story:
Storm damage claims are tied to a date. The adjuster will ask which event caused the damage, and the policy sets the deadline for reporting it. Three events from 2024 are still producing claims across Cypress, Katy, Spring and The Woodlands:
Both adjusters and roofers use a test square: a 10-by-10-foot area marked on each slope. If a square shows roughly eight or more hail hits, that slope is generally considered a total loss. A hit on one slope with the rest clean is a repair. Hits across most slopes is a replacement, and after a storm like May 28 that is the more common finding, because hail does not choose slopes.
Age changes the math. On a roof that is 15 or more years old, replacing one slope leaves you with new shingles that will not match and a roof that still has four old slopes. Most Texas policies have no matching clause, so the carrier can pay for the one slope. Where the shingle line has been discontinued, a supplement with the manufacturer's discontinuation notice sometimes changes that outcome.
Our inspection gives you the slope-by-slope count and the photos either way. The repair-or-replace call should be made on that evidence, by you, not by whoever is standing in your driveway with a clipboard.
A hail repair limited to a slope or two, with some flashing and a vent or two replaced, typically runs $300 to $3,500 in the Houston area. A full replacement with architectural asphalt shingles runs about $4.50 to $8.50 per square foot installed, which puts most Cypress, Katy and Spring homes between $12,000 and $25,000. Class 4 impact-resistant shingles add roughly $1 to $2 per square foot.
On an approved claim, your cost is the deductible, usually 1 to 2 percent of your dwelling coverage, so $4,000 to $8,000 on a $400,000 policy. Texas law prohibits any contractor from paying, waiving or rebating that deductible. The one who offers to is telling you how the rest of the job will go.
| Scope | Typical Houston-area cost | On an approved claim |
|---|---|---|
| Repair, one or two slopes | $300 – $3,500 | Deductible, if above it |
| Full replacement, architectural shingles | $12,000 – $25,000 | Deductible |
| Upgrade to Class 4 impact-resistant | +$1 – $2 per sq ft | Usually homeowner-paid; premium discount after |
Hail is a covered peril on nearly every Texas policy. The questions are how much it pays and by when you have to ask. Four clauses decide it:
The order matters, because the file you build in the first week is what the claim is settled on.
The three jobs below are typical of what a hail-and-wind claim looks like from tarp to finished roof in our home market. Each page has the photos. Barker Grove Ln and Dakota Hill Ct in Cypress went from an emergency tarp to a full replacement paid at the approved scope; Peach Knoll Ln in Katy started as a temporary repair and ended as a full replacement once the adjuster saw the slope count.
Check the soft metal first: gutters, downspouts, vent caps and the AC condenser fins. Dents there mean the shingles took the same hits. Granule piles at the downspouts and splatter marks on the driveway confirm it. Then book a free inspection; the bruises themselves are only visible on the roof.
A repair confined to one or two slopes typically runs $300 to $3,500. When the hits cover most of the roof, it is replaced instead at roughly $4.50 to $8.50 per square foot for architectural shingles, or $12,000 to $25,000 on most northwest Houston homes. On an approved claim you pay the deductible.
Yes, hail is a covered peril on nearly every Texas policy. What varies is the payout: actual cash value on older roofs, cosmetic exclusions on metal, a separate 1 to 2 percent wind-and-hail deductible, and a one-year window from the storm date to report it.
Check your policy, but most now require storm losses to be reported within one year of the event. Because hail damage often does not leak for a year or two, the inspection should happen right after the storm, not after the leak.
Usually not. Most Texas policies have no matching clause, so the carrier can pay to replace the damaged slope only. If the shingle has been discontinued, a supplement with the manufacturer's notice sometimes extends the scope. Our inspection documents both the damage and the product so you can make that case.
If you are replacing anyway, yes in most cases. Class 4 shingles add about $1 to $2 per square foot, most Texas carriers discount the wind-and-hail portion of the premium for them, and they are the one upgrade that changes what the next storm does to the roof.
We inspect for free, photograph what we find, and put the quote in writing.
Squares, pitch, material, tear-off layers, decking and permits: what each line of a Houston roof quote pays for, and when insurance covers the replacement.
Lifespan, heat, wind, hail, insurance discounts and HOA rules compared for Houston homes, and how to decide which roof fits how long you plan to stay.
It is the most-asked question on Houston roofing searches, and it is a Florida rule. What Houston's code actually requires on a repair or replacement, and what matters for your claim.
Talk to Houston Strong Roofing. The inspection and written quote are free.